


- Scaling specialty coffee isn’t all it’s made up to be – big brands are craving the creativity of their early days
- Side projects like Blue Bottle Studio and Starbucks Reserve help reignite passion while big brands juggle profits
- With food costs up 29% and labour up 31%, small, focused coffee shops are proving size isn’t everything
FOR many owners of specialty coffee brands that have scaled, success hasn’t been all fun and games.
The dream of building a chain or a significant operation, fuelled by the prospect of growth and market influence, has often collided with the reality of rising costs, complex logistics, and the challenge of catering to a broad consumer base.
“Discipline and drive are great assets for specialty coffee brands that wish to overcome these challenges and grow in controlled, responsible ways,” says Brian Gaffney, Chief Experience Officer at Caravela Coffee.
“Founders and leaders must be clear as to why they are growing and communicate the impact they expect the desired growth to have on their financial performance, operating models, and customer and supplier relationships. Growth for growth’s sake is risky.”
As these brands grow, they face mounting responsibilities: managing a large staff, maintaining expensive infrastructure, complying with extensive regulations, and, crucially, ensuring profitability while appealing to mainstream tastes.
“Scaling a business is undeniably challenging,” says Nick Mabey, Co-Founder and Director of Assembly Coffee. “One major hurdle occurs in what we often call the ‘death zone’ – when revenue is around $3 million and you’re trying to double that figure. The complexities of scaling multiply significantly at this stage.”
This dynamic has pushed some founders and senior executives of scaled specialty coffee brands to yearn for the simplicity and creativity of their early days.
To side step the binary choice of “big or small,” a growing number of these leaders are now launching or considering smaller, niche “passion projects.” These side brands focus on artisanal craftsmanship and niche clientele, offering a counterbalance to their scaled ventures.
For instance, Blue Bottle Coffee, which scaled dramatically after a majority acquisition by Nestlé in 2017, continues to operate under corporate oversight. Yet a nostalgia for its early days of experimentation and community engagement seems to surround the operation – James Freeman’s most recent niche passion project, Blue Bottle Studio, seems to be an expression of that longing.
Similarly, brands like Intelligentsia and Stumptown, pioneers of the specialty coffee wave that have since been acquired by larger corporations, have seen their original founders step away or express interest in smaller, more manageable ventures. Doug Zell – the founder of Intelligentsia Coffee – launching the niche cafe The Meteor is one case is point.
Even global coffee chains are feeling the pull toward niche endeavors. Starbucks recently launched its Reserve Roasteries, designed to capture the essence of small-scale specialty coffee experiences within its larger brand framework. These roasteries, though technically part of Starbucks, are often treated as passion projects that harken back to the intimacy and exclusivity of specialty coffee’s roots.
“Big brands have long tried to capture the independent market with spinoffs like Lincoln and York, Taylors of Harrogate, or Starbucks Reserve – and that will continue,” says Nick.
“Smaller, nimble brands can constantly innovate, but once you grow, innovation often gives way to meeting commercial KPIs, especially with investors involved. Creativity then shifts from true innovation to a focus on marketing and ROI.
The golden days of specialty coffee
Before the rise of specialty coffee chains, the industry was characterised by the small, dynamic operations that set the tone of the industry we know today in terms of innovation, style, and customer experience.
In the late 1990s and early 2000s, coffee roasters and café owners saw an opportunity to redefine the beverage.
They cultivated communities around their shops, took creative risks with experimental brewing methods, and focused on quality over quantity. These were the golden days of specialty coffee, where passion and profitability often went hand in hand.
“Back in the day, the coffee market was less saturated, making it easier to position yourself as a coffee-focused brand,” says Nick.
“Ten years ago, the industry was immature, with fewer competitors and lower standards for quality and innovation, so becoming a market leader was relatively straightforward. Today, it’s much tougher, with countless brands vying for attention in a market where consumers increasingly use coffee, like fashion, to express their identity.”
Small operations thrived because of low overheads and direct customer relationships. Profit margins were high, driven by the loyalty of niche clientele who valued craftsmanship and quality over convenience.
“Looking back at the early days of specialty coffee, I believe that the rising tide lifted all brand boats,” says Brian. “It was relatively easy to introduce specialty coffee to new people in new places, and at new, higher price points. Decisions to expand and scale were organic and responsive to a curious and open-minded market that was eager to experience this new, affordable, culinary luxury.
The products and services wrapped around them were innovative and performative. For a while, curiosity bested convenience as customers willingly waited in line for a coffee prepared just for them, often in front of them. In those days, specialty coffee was like a new music genre that was both developing its sound and defining its fan base.”
The industry’s intimate scale allowed for creativity, innovation, and the cultivation of unique brand identities. It was a time when owners were both artisans and entrepreneurs, and every decision felt like a personal expression of their vision.
However, the success of specialty coffee began to attract larger audiences and bigger opportunities. Many of these small brands decided to scale, driven by a mix of ambition and economic pragmatism.
Chains like Blue Bottle, Stumptown, and Intelligentsia expanded their footprints, while smaller brands aspired to replicate their success.
The shift promised larger profits and market share but also required compromises: streamlining operations, appealing to a broader (and often less discerning) customer base, and shouldering the burdens of larger operations.
As these brands scaled, some founders discovered the hidden costs of success. Taxes, real estate, labour laws, and corporate structures ate into margins. Creativity gave way to consistency, and the sense of community diminished.
What had once been a passion-driven venture became a balancing act of spreadsheets, supply chains, and investor expectations.
“Over time, the industry has matured,” says Brian. “What used to simply be ‘specialty coffee’ has fragmented into sub-genres, creating an economic reality in which decisions to expand and scale are driven by pressures to win in the market by managing costs and maximising sales better than a brand’s competitors.
Whereas growth was once fuelled by finding customers new to specialty coffee, it is now about compelling customers from competing brands. Specialty coffee, as an industry, is fully in its ‘chess, not checkers’ phase.”
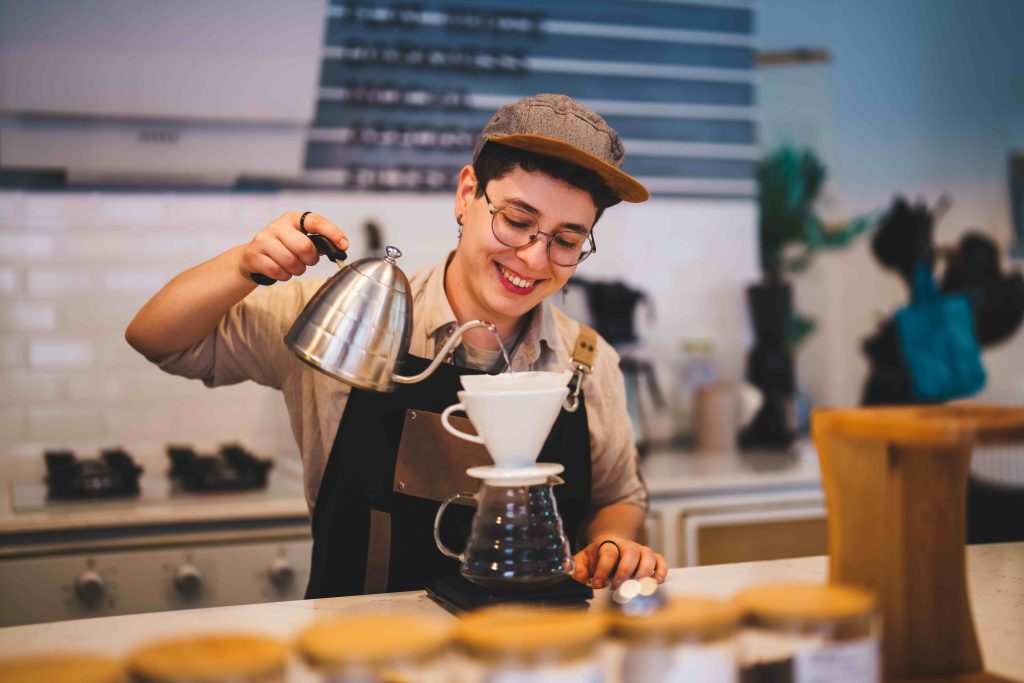
The future of specialty coffee: Big brands as incubators for small creative projects?
Today’s economic landscape is creating conditions that may favour a return to the smaller, more agile specialty coffee operations of the past.
Rising costs, labor shortages, and increasing taxes are squeezing margins for large-scale operations. In contrast, small, tightly run businesses can operate with fewer staff, lower overheads, and greater efficiency.
The numbers tell a story: A survey made across specialty coffee consumers in the Gauteng area of South Africa found that 81% of participants regarded coffee quality as a high priority, followed by 52% valuing customer service, and 31% considering it essential – making small shops valued candidates. Meanwhile, In the last 4 years, food costs for the average restaurant have gone up 29%, while at the same time labour costs have gone up 31% – making scaling a challenge.
Some brands have already embraced this shift. Smaller specialty coffee operations, like Los Angeles-based G&B Coffee, are thriving by focusing on high-quality, niche offerings and maintaining a manageable scale.
“Smaller brands must work harder and more creatively than ever to develop and deliver their brand’s unique perspective on specialty coffee in a very saturated market to consumers suffering from attention deficits and media distractions,” says Brian.
By staying small, these businesses can maintain strong profit margins, adapt quickly to market trends, and cater to customers who value exclusivity and craftsmanship.
However, it is unlikely that the specialty coffee industry will abandon scaling altogether.
“There’s growing pressure on small single-site café operators,” says Nick.
“While entry is easy, profitability is the real challenge. Expanding into multiple sites adds operational complexity and financial strain, which is where many chains fail. Timing and strategy are key – you can either miss the mark by staying too small or overextend by growing too fast. Watch House is a good example of getting this balance right, although time will tell if their aggressive strategy will be sustainable in the long run.”
Instead, many brands are exploring hybrid models: maintaining their larger operations while launching smaller, passion-driven side projects. These side projects allow them to recapture the creativity and community engagement of their early days while leveraging the resources of their scaled brands.
Starbucks Reserve Roasteries are one example; others include La Colombe’s Draft Latte, a niche product line marketed as a return to artisanal roots, and independent ventures started by former specialty coffee executives.
The question remains whether the specialty coffee industry will come full circle – returning to the small, creative operations that once defined it – or evolve into a dual structure where large brands coexist with smaller, passion-driven side projects.
“To reach a new audience, you often need to create distinct values, which may require separate brands,” says Nick.
“For example, we operate two brands to cater to both existing and new audiences. As a predominantly B2B business, we focus on aligning our offerings with the specific expectations of this sector, tailoring our specialty coffee positioning to resonate with business customers – something others may struggle to achieve.”
What seems certain is that the industry will continue to grapple with the tension between scale and specialisation, efficiency and artistry.
“I foresee a future where larger coffee brands will explore and embrace exclusive, limited, passion-fuelled projects as part of their product and experience strategy,” says Brian.
“Starbucks’ Reserve program and Nestle’s acquisition of Blue Bottle are foundational precedents for such a strategy. Going forward, I can imagine more large brands adopting this practice to attract new customers, premiumise product offerings, and improve sales revenue.
However, unlike the smaller operators, these large- brand led passion-fuelled projects may not carry the same demand for profitability. Larger competitors may be able to run such programmes as loss leaders, as they are able to generate additional revenue from higher margin products within their core offerings.”
The nostalgia for the golden days of specialty coffee is more than just wistful thinking; it is a reaction to the challenges and compromises of scaling. As economic pressures mount and consumer preferences shift toward authenticity and exclusivity, the appeal of smaller, more focused operations is growing.
“Staying true to creativity is about maintaining consistent brand values, which can be successfully scaled without compromise – if done right,” says Nick.
“Many brands fail because they get distracted by focusing too heavily on one corner of the market. Grind is a clear example: their history and trajectory show how they’ve adjusted their model and brand integrity to target a very specific market.”
Whether the future lies in a return to the simplicity of small operations or in hybrid models that blend scale with passion, one thing is clear: the specialty coffee industry is poised for a new era of experimentation and reinvention.
For many, that journey will begin by looking back to the intimate, creative spaces where it all started.
Coffee Intelligence
Want to read more articles like this? Sign up for our newsletter here.


